Warehousing & 3PL in Sweden, Norway, Finland or Denmark
The Nordic region, comprising Sweden, Norway, Denmark, and Finland, offers a robust and sophisticated logistics market for businesses seeking expansion. This guide provides a strategic overview of the region's warehousing and 3PL landscape, focusing on key regional hubs, country-specific market dynamics, prevalent trends, and crucial considerations for market entry.
The Nordics at a Glance
| Sweden | Norway | Denmark | Finland | |
|---|---|---|---|---|
| Standard VAT | 25% | 25% | 25% | 25.5% |
| Customs border | No borderInside the EU customs union | Customs borderEEA, outside the EU customs union | No borderInside the EU customs union | No borderInside the EU customs union |
| B2C VAT scheme | EU OSS | VOEC, up to NOK 3,000 per item | EU OSS | EU OSS |
| VAT representative | Not required | Required, unless established in a covered EEA state or the UK | Not required | Not required |
| Currency | Swedish krona (SEK) | Norwegian krone (NOK) | Danish krone (DKK) | Euro (EUR) |
| Last mile | PostNordHome delivery preferred (32%) | Posten BringLetter box preferred (31%) | PostNordService point preferred (45%) | PostiParcel locker preferred (37%) |
- 1. Standard rates as at September 2026. Finland has applied 25.5% since 1 September 2024; its reduced rate dropped to 13.5% on 1 January 2026. Denmark, Sweden and Norway have applied 25% for decades.
- 2. VOEC covers B2C sales of goods up to NOK 3,000 per item, shipping excluded. Registration becomes mandatory once sales to Norwegian consumers pass NOK 50,000 in a twelve-month period. See Norwegian Customs on the VOEC scheme.
- 3. A Norwegian VAT representative is not required if you are established in an EEA state covered by Norway’s agreement on administrative cooperation and recovery of VAT claims, or in the United Kingdom. Businesses established elsewhere must register through a representative. See Altinn on VAT for foreign companies.
- 4. Delivery preference is the share of consumers naming that option as their preferred delivery method, PostNord e-commerce survey, spring 2025.
Understanding the Nordic Logistics Landscape
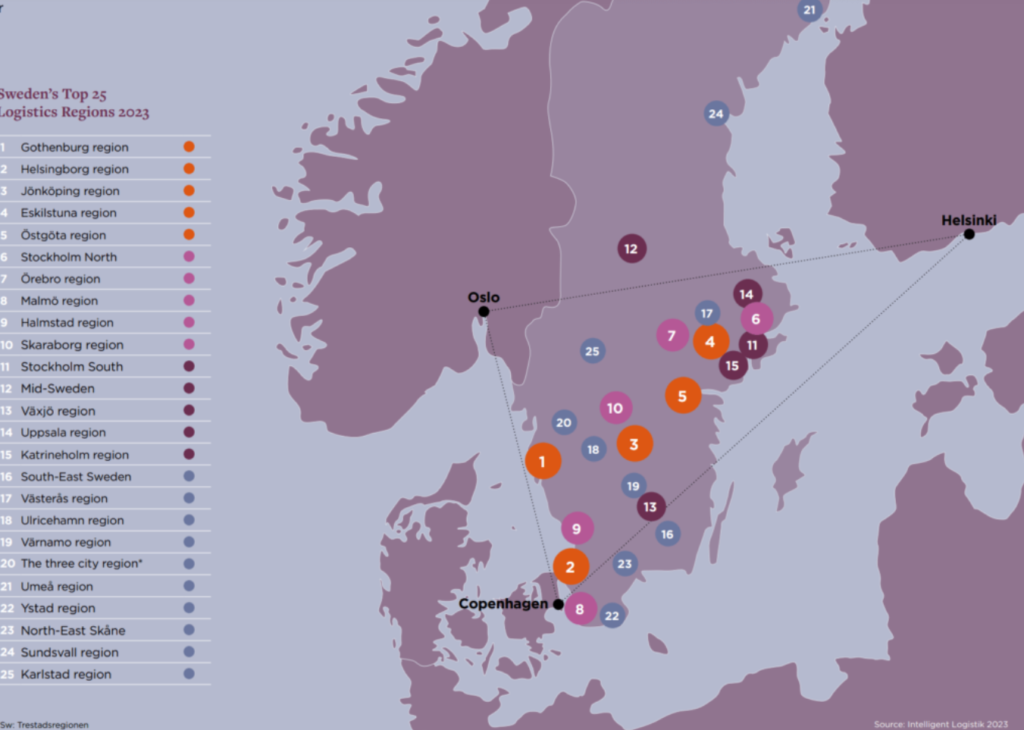
The region benefits from high digitalization, advanced infrastructure, including the crucial "Nordic Trade Triangle" connecting capital cities, and a strategic European location. However, operational costs tend to be higher than in many other European areas. This necessitates careful planning, talking to the right people and understanding of each market's nuances. One thing is certain: The Nordic countries offer affluent consumer bases, stable business environments, and attract substantial international investment in logistics, signaling confidence in the region's long-term potential.
Key Logistics Hubs and Regions in the Nordics
Sweden:
- Stockholm North: The largest logistics hub in Sweden (14% market share in 2023). Benefits from proximity to the capital and Arlanda Airport. High demand but increasing vacancy rates warrant careful site selection according to CBRE.
- Gothenburg Region: Major port city and second largest logistics hub (12% market share). Focus on maritime logistics and access to western Sweden. Maintaining low vacancy rates compared to other regions.
- Jönköping Region: Central location within the Nordic Trade Triangle (12% market share). Offers good connectivity to all Nordic countries. Experiencing higher vacancy rates due to recent speculative development.
- Helsingborg Region: Southern hub (9% market share). Gateway to continental Europe via ferry connections. Offers strategic positioning for businesses targeting both Nordic and European markets.
- Malmö Region: Growing logistics hub in southern Sweden, benefitting from the Öresund Bridge connection to Denmark and mainland Europe. Focus on cross-border trade.
Norway
Norway's logistics landscape is heavily influenced by its unique geography, dispersed population, and historical ties to the oil and gas industry. While Oslo dominates as the main consumption and distribution center, other regional hubs cater to specific industries and geographic areas. The increasing focus on sustainability and the rise of e-commerce are also shaping the market.
- Oslo Region: Undeniably the heart of Norwegian logistics, the Oslo region benefits from its high population density, strong consumer market, and position as the country's primary import/export gateway.
- Strengths: Modern facilities are in high demand, driven by e-commerce growth and the need for efficient distribution. Excellent transport connections by road, rail, air (Oslo Airport, Gardermoen), and sea.
- Weaknesses: Limited land availability and high real estate costs. Rising vacancy rates, particularly in older, less efficient properties (CBRE, H1 2024), highlight the importance of securing modern spaces.
- Opportunities: Growth in e-commerce and the increasing demand for sustainable logistics solutions present opportunities for specialized 3PL providers and developers of green warehousing.
- Bergen Area: Serving as Western Norway's main logistics hub, Bergen holds a strategic position for maritime logistics, supported by its large port and historical ties to the shipping industry.
- Strengths: Specialized expertise in maritime logistics, including handling of offshore equipment and goods. Growing focus on renewable energy and aquaculture creates new logistics demands.
- Weaknesses: Less developed infrastructure compared to Oslo. Distance from the main population centers can pose logistical challenges.
- Opportunities: The energy transition and growth in aquaculture create significant opportunities for logistics providers with expertise in these sectors.
- Stavanger Region: This region's logistics activities are heavily intertwined with the oil and gas industry. Stavanger boasts specialized infrastructure and a highly skilled workforce catering to this sector.
- Strengths: Deep expertise in handling complex and demanding logistics operations for the oil and gas industry. Well-established supply chains and specialized infrastructure, including the Port of Stavanger.
- Weaknesses: Dependence on the oil and gas sector makes the region vulnerable to fluctuations in energy markets. Limited diversification into other logistics segments.
- Opportunities: While remaining a niche market, the Stavanger region could see opportunities in supporting offshore wind farm development and other renewable energy projects.
- Trondheim Region: Central Norway's largest city and an important logistics hub serving the region's population and industries.
- Strengths: Strategic location with good road and rail connections. Growing industrial base and consumer market. Trondheim Airport, Værnes, provides airfreight capacity.
- Weaknesses: Smaller market size compared to Oslo and Bergen. Limited specialization in specific logistics segments.
- Opportunities: Growth in e-commerce and the need for regional distribution centers present opportunities for logistics providers.
- Eastern Norway (around the Swedish border): This area, including regions like Østfold and Hedmark, benefits from its proximity to Sweden and offers potential for cross-border logistics operations.
- Strengths: Lower operating costs compared to Oslo. Strategic location for serving both Norwegian and Swedish markets. Good road and rail connections to Sweden.
- Weaknesses: Less developed warehousing infrastructure compared to the main hubs. Dependence on cross-border trade flows.
- Opportunities: Growing cross-border e-commerce and the need for efficient and sustainable logistics solutions could create opportunities for specialized 3PL providers.
Mapping Norway's Logistics Hubs
This interactive map reveals Norway's warehousing and 3PL landscape. The map identifies several distinct logistics regions, each serving different market needs. The Greater Oslo Region dominates as the primary warehousing cluster, offering modern facilities but facing high costs and land scarcity. The Eastern Border Zone leverages lower operating costs and Swedish proximity, making it attractive for cross-border operations. Meanwhile, specialized hubs in Bergen, Stavanger, and Trondheim serve regional markets and specific industries like maritime, energy, and aquaculture. The transport network connecting these hubs includes major road corridors, rail lines, and shipping routes, enabling both domestic distribution and international trade connections through key ports and border crossings.
- Industry Focus: Aligning your chosen hub with your industry's specific needs is paramount. Oil & Gas? Stavanger. Maritime or Aquaculture? Bergen. General distribution/consumer goods? Oslo or Trondheim.
- Cost vs. Access: Balance the lower operating costs of regional hubs with the superior access and infrastructure of the Oslo region.
- Sustainability: Consider the availability of green warehousing and sustainable logistics solutions, which are increasingly important in Norway.
- Future Growth Potential: Assess the long-term growth potential of each region, factoring in industry trends and demographic shifts.
Denmark
- Greater Copenhagen: Primary hub with a strong pharmaceutical and e-commerce focus, serving as a Nordic distribution center. Limited land availability necessitates careful planning (CBRE, Q2 2024).
- Jutland Triangle: Manufacturing-oriented region with excellent access to the German market via robust transport links. Suitable for businesses involved in industrial production and distribution.
- Aarhus Region: Denmark's second-largest city, growing logistics hub with focus on e-commerce and retail distribution.
Example: What Does Nordic Fulfillment from Denmark Cost?
The geographic location of your fulfillment center is a critical factor in optimizing delivery speed. A warehouse situated in Denmark, for example, functions as a powerful launchpad for the entire Nordic region and beyond. Its position within the crucial "Nordic Trade Triangle" connecting the capital cities makes it an ideal hub for efficient distribution. This strategic focus aligns with Denmark's broader logistics landscape, which is concentrated in three main hubs: Greater Copenhagen for Nordic distribution, the Jutland Triangle for access to the German market, and the growing Aarhus Region for retail and e-commerce.
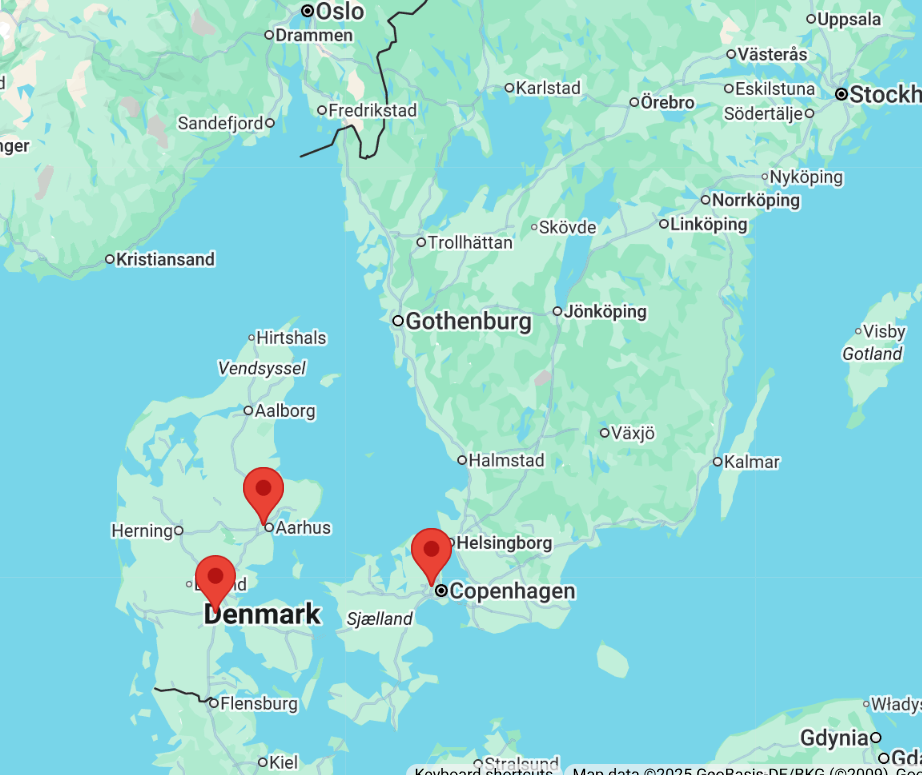
This positioning is further enhanced by direct linehaul connections from Denmark into key German and Dutch hubs and from there to the rest of Europe, making it a powerful dual-purpose base for serving both the Nordics and Northern Europe.
This allows for competitive delivery timelines from a single inventory location:
- Denmark: Day 1 delivery is achieved for over 99.5% of all orders.
- Sweden: Day 1 delivery is possible for over 78% of orders, primarily to core southern and central regions, with other areas typically served within 2-3 days.
- Norway: Major postal codes (0015-3999) can be reached in 1-2 days.
- Finland: Core areas are generally served within 2-3 days.
A key consideration for businesses targeting Norway is that it is not an EU member state and therefore not a part of the customs union.
Warehousing & Operational Costs in Denmark
Understanding your operational costs is crucial for financial planning. Based on our market research, the following cost structure is representative of what a competitive 3PL provider in the Danish market may offer. While rates will vary between providers, this breakdown illustrates the key fees to expect.
- Goods Receipt: The initial intake and processing of your inventory is typically billed at an hourly rate, which often falls in the 350-450 DKK (approx. €47-60) per hour range.
- Monthly Storage: Costs vary based on the storage method required.
- Pallet Storage: For bulk inventory, a standard EUR-pallet may cost around 45-70 DKK (approx. €6-9.50)/month depending on its height.
- Bin Storage: For individual items in the pick-face area, costs are scalable, typically ranging from 7-20 DKK (approx. €1-2.70)/month depending on the size of the bin location used. This model offers flexibility for growing businesses.
- Fulfillment (Pick & Pack): This is the primary transactional cost associated with each customer order.
- Order Fee: Expect a fixed charge to initiate the processing of an order, often between 12-15 DKK (approx. €1.60-2.00).
- Item Fee: A variable charge for each unit picked within that order, typically between 4-6 DKK (approx. €0.55-0.80) per item.
Example Calculation: A B2C order containing three items could have a fulfillment cost of:
12-15 DKK (Order Fee) + (3 items × 4-6 DKK) = 24-33 DKK (approx. €3.20-4.45)
(This calculation precedes packaging materials and last-mile shipping costs).
- Returns Management: A standard fee for processing a returned order is often around 18-22 DKK (approx. €2.40-3.00), with more complex inspections or handling billed at an hourly rate.
Specialized Focus: Food & Nutrition Logistics in the Nordics
Food and nutrition businesses face additional complexity beyond standard fulfillment. Specialized handling for batch tracking, expiry date management (FEFO systems), and temperature control are non-negotiable for this sector.
Key Considerations for Food Products:
- Batch & Expiry Management: Your 3PL must handle FEFO (First Expired, First Out) systems to prevent waste and ensure consumer safety
- Inbound Quality Control: Visual inspection on arrival to identify damaged goods, critical for gels, powders, and supplements
- Regulatory Compliance: GDP standards for certain products, food-grade facility requirements
Typical Cost Structure (Denmark-based example):
- AutoStore Bin: ~DKK 19/month (full), ~DKK 12/month (half)
- Pallet Storage: From DKK 49/month (small pallet)
- Order Processing: DKK 13.50 startup + DKK 4.75 per item
- Returns: Per-order fee + hourly processing rate
Note: Most agreements include annual index adjustments and clauses for immediate price increases due to energy/raw material cost spikes. For Norway (non-EU), choose a 3PL with Norwegian operations to streamline customs and VAT processes.
Analysis of Last-Mile Delivery Costs
The final cost to ship a parcel is determined by its destination, weight, and service level. Shipping rates are based on the chargeable weight, which is the greater of the parcel's actual physical weight or its volumetric weight.
Based on our research of major carriers for shipments originating from Denmark to a local pick-up point, businesses can expect costs to fall within these general ranges:
- For a standard small parcel (e.g., 1-3 kg), domestic shipping within Denmark is the most economical, with prices typically in the range of 25-30 DKK (approx. €3.35-4.00).
- Shipping the same parcel cross-border to other EU countries in the Nordics, like Sweden or Finland, will generally range from approximately 35 DKK to 55 DKK (approx. €4.70-7.40), depending on the exact weight and destination.
- For non-EU shipments to destinations like Norway, which require customs processing, costs are higher, typically ranging from 80 DKK to 90 DKK (approx. €10.75-12.10) for a similar-sized parcel sent as part of a bulk shipment.
By carefully analyzing these three components—strategic location, operational fees, and delivery rates—a business can effectively forecast its logistics expenses and select a 3PL partner equipped to support a successful and scalable Nordic expansion.
To find a warehousing location in Denmark you can contact us (leave your details in the contact form at the bottom of this page). Another great way is the platform lokaleportalen.dk(opens in new tab). You can filter out the right warehouse providers. We recommend you to work with a lessor that is established and has 10+ years in the business.
Finland
- Helsinki Metropolitan Area: The country's main logistics hub with port access and international connections. Benefits(opens in new tab) from improving I&L sector sentiment (CBRE, Q2 2024).
- Tampere Region: Central location with an industrial focus, serving as a key center for domestic distribution. Attractive for businesses targeting the Finnish market.
- Turku Region: Important port city with growing logistics activity. Focus on maritime logistics and connections to Southwest Finland.
Nordic E-commerce: Who Sells, Who Buys, and What That Demands of Your Warehouse
Warehousing decisions in the Nordics follow the sales channel. Four countries, four currencies in daily use, three postal incumbents and one customs border sit between you and roughly 28 million consumers, and your channel mix decides how many of those you actually have to deal with. This section covers the demand side of the market and translates it into requirements you can put in front of a 3PL provider.
The Size and Shape of Nordic Online Demand
Sweden is the largest of the four online retail markets. ECDB puts Swedish online retail revenue at roughly USD 13 billion in 2023 with a forecast of about USD 17 billion for 2026, ahead of Denmark and Finland at roughly USD 8 billion and USD 7 billion. Norway is smaller in absolute terms and the fastest growing of the group, at an expected 8.7 percent for 2026 against 8.6 percent for Sweden. Treat all four as modelled estimates rather than audited numbers, since definitions of what counts as online retail differ between sources and totals move by billions depending on whether services and travel are included.
One number matters more to a foreign business than market size: how open these markets already are to buying from abroad. PostNord found that 73 percent of Nordic consumers had bought from a foreign website in the past year and that 48 percent do so every month. Nordic shoppers are comfortable ordering across borders, reading English product pages and paying in another currency. What they will not accept is slow delivery, a return process that requires a printer, or an unexpected customs bill at the door.
Clothing is the largest category in all four countries, with health and beauty second in Denmark, Sweden and Norway. Second-hand trade is not a fringe segment either: 32 percent of Nordic consumers bought something second-hand online in the past month, which is the context for the classifieds platforms further down.
Direct-Selling Marketplaces
Marketplace coverage in the Nordics is fragmented. No single platform carries a serious share of all four countries, and the local category leaders are stronger than most international sellers expect. PostNord names Amazon the most used marketplace in Sweden, Zalando in Denmark and Finland, and Temu in Norway, which tells you how little the region behaves as one market.
| Platform | Country coverage | Focus | What it means for fulfilment |
|---|---|---|---|
| Amazon | Local site in Sweden only; Denmark, Norway and Finland served through amazon.de and amazon.co.uk | General merchandise | No Amazon fulfilment node inside Denmark, Norway or Finland. FBA stock for the region sits in Sweden or continental Europe. |
| Zalando | All four | Fashion and lifestyle | Partner Program with platform-fulfilled or seller-fulfilled options. Strict labelling, cut-off times and returns SLAs. |
| Boozt | All four, strongest in Denmark and Norway | Premium fashion and beauty | Inbound goes into its automated warehouse in Ängelholm, Sweden, around 88,000 square metres with 1,300 robots. Expect carton, pallet and barcode compliance rules. |
| CDON | All four | General marketplace | Seller-fulfilled. You carry the delivery promise, so a Nordic stock location is what makes the listing competitive. |
| Verkkokauppa.com | Finland | Electronics and tech | Around 14 percent of Finnish desktop marketplace visits. Domestic delivery and service expectations apply. |
| Elkjøp Group (Elkjøp, Elgiganten, Gigantti) | All four | Electronics retail | A retail supply relationship rather than an open marketplace: EDI, booking slots, pallet labels and GS1 barcodes. |
| Komplett | Norway, Sweden | Electronics, IT and gaming | Strong in B2B and professional segments. Serialised goods and warranty flows. |
| Adlibris | All four | Books, media and games | High order counts of small items. Letterbox-format packaging pays for itself. |
| Temu and Shein | All four | Cross-border value retail | Few brands sell through them, yet they have reset delivery-time and price expectations and account for much of the growth in customs handling volume into Norway. |
The Amazon line deserves emphasis because it decides where inventory sits. Amazon opened a local storefront in Sweden in October 2020 and has not added one in the other three countries. If you fulfil through FBA, your Nordic stock is physically in Sweden or continental Europe, and every Norwegian order crosses a customs border on the way out. Sellers who want next-day coverage of Denmark and Norway usually reach it through a Nordic 3PL rather than through the marketplace network.
Classifieds and Second-Hand Platforms
International sellers routinely miss the classifieds layer. The four national sites are FINN in Norway, Blocket in Sweden, DBA in Denmark and Tori in Finland, and all four belong to the same owner, Vend Marketplaces ASA, renamed from Schibsted Marketplaces in the second quarter of 2025. Tradera covers auctions in Sweden and Lauritz the art, antiques and design segment in Denmark.
| Platform | Country | Typical use | Why it matters to logistics |
|---|---|---|---|
| FINN.no | Norway | Vehicles, property, jobs, general goods | The default search surface for Norwegian buyers. Price expectations are set here before a customer reaches your webshop. |
| Blocket.se | Sweden | Home, electronics, vehicles, services | Heavy price benchmarking. Strong outlet for B-stock and end-of-line inventory. |
| DBA.dk | Denmark | Home goods, electronics, vehicles | Useful for testing demand on bulky items before committing warehouse space to them. |
| Tori.fi | Finland | Home, vehicles, services | Widely used for price research ahead of a marketplace purchase. |
| Tradera.com | Sweden | Auctions and collectibles | Single-item picking, non-standard packaging, individual dispatch. |
| Lauritz.com | Denmark | Art, antiques and design auctions | High-value, fragile and oversized handling with photo documentation. |
These platforms belong in a warehousing article for two reasons. They set the price expectation your new goods are measured against, and they are the natural liquidation channel for returns, B-stock, refurbished units and discontinued lines. A 3PL that can grade and photograph returned goods, hold them under a separate stock status and dispatch single items to private addresses is doing recommerce work. Price that as handling time, not as standard pick and pack.
Payments and Checkout
Payment preferences are national, and a checkout that ignores them loses carts before logistics ever becomes the issue.
- Sweden: Swish for instant mobile payment, with more than eight million users, alongside Klarna invoice and instalment options.
- Norway: Vipps, used by more than half the population.
- Denmark: MobilePay, with roughly four million users, and the Dankort debit card.
- Finland: cards plus direct online bank payment, which remains the most trusted route for many Finnish shoppers.
Vipps and MobilePay have been a single company since their 2022 merger, so a payment provider that supports one usually covers the others. The warehouse consequence sits in the pay-later methods that dominate Sweden and Norway: money is often collected after delivery, so returns have to be registered quickly and accurately. A parcel that sits unscanned in a returns area for a week turns into a payment dispute and a support ticket.
Delivery and Returns Expectations
Nordic consumers are specific about how goods reach them, and the preference differs by country. PostNord recorded the following in its spring 2025 survey.
- Denmark: 45 percent prefer a service point.
- Finland: 37 percent prefer a parcel locker.
- Sweden: 32 percent prefer home delivery.
- Norway: 31 percent prefer delivery to the letter box.
- Across the region, 77 percent name flexibility in choosing the pickup location as the most important factor.
- 62 percent paid for their most recent delivery, so free shipping is not a universal expectation.
Charging for delivery is normal in the Nordics. Being inflexible about where the parcel lands is not. The incumbent carriers differ per country as well: PostNord in Sweden and Denmark, Posten Bring in Norway and Posti in Finland. A 3PL with a single carrier integration will quietly limit which of the preferences above you can serve, so ask which carriers are live in the warehouse management system per destination country. Norwegian letter-box preference also has a packaging consequence: flat packaging that fits a mailbox avoids a pickup-point trip and removes a step from the customer experience.
Returns are the other half of the equation. Free and simple returns are a baseline expectation rather than a differentiator, return rates in fashion run high enough to change unit economics, and the return fee structure quoted earlier in this article is the line item to negotiate hardest. Ask whether returns are billed per order or per hour, what inspection is included at that price, and how quickly a returned unit is back in sellable stock.
Norway, VOEC and the Customs Border
VOEC applies
- The buyer is a private consumer in Norway. VOEC is a B2C scheme only.
- The item is worth up to NOK 3,000, shipping excluded.
- The goods are shipped to Norway from outside the country.
- You charge and display 25% Norwegian VAT at checkout and report it quarterly.
- Registration is mandatory once sales to Norwegian consumers pass NOK 50,000 in twelve months.
Ordinary import rules apply
- The customer is a Norwegian business. B2B sits outside VOEC.
- The item is worth more than NOK 3,000.
- The goods are foodstuffs, beverages, supplements or vitamins.
- The goods are alcohol, tobacco, restricted goods, or subject to excise duty.
- You already hold stock inside Norway.
In the second column the shipment needs a customs declaration and import VAT at the border, which in practice means a Norwegian importer of record or a 3PL with Norwegian operations. Returns need a documented re-export and re-import route as well, or duty and VAT are paid twice on the same item.
Norway is in the EEA but outside the EU customs union, so every consignment is a customs event. The VOEC scheme, short for VAT on E-Commerce, lets a foreign seller charge Norwegian VAT at checkout on goods below NOK 3,000 per item, shipping excluded, and report it quarterly. Registration becomes mandatory once sales to Norwegian consumers reach NOK 50,000 within a twelve-month period. Three limits matter operationally.
- VOEC covers B2C sales only. Business customers fall outside it.
- Foodstuffs, beverages, non-medicinal dietary supplements and goods subject to excise duty are excluded. Food and supplement brands therefore cannot use VOEC and normally need either a Norwegian importer of record or a 3PL with Norwegian operations, which is the same conclusion the food and nutrition section above reaches from the storage side.
- Items above NOK 3,000 follow ordinary import procedures, with a customs declaration and import VAT at the border.
Returns add a second layer. Goods sent back from Norway to an EU warehouse need a documented re-export and re-import route, otherwise duty and VAT are paid twice on the same item. Ask any prospective provider how it handles Norwegian returns before signing anything.
Channel Integration and What to Ask a Nordic 3PL
Selling through a webshop, two or three marketplaces and a retail chain at the same time means order data arrives in different formats under different rules. Feed and channel management tools such as ChannelEngine or Lengow, or a middleware layer with a proper order management system, sit between those channels and the warehouse. The integration questions decide more about day-to-day performance than the storage rate does.
- Real-time stock synchronisation, so marketplace listings do not oversell shared inventory.
- Per-channel packing and documentation rules, including marketplace-specific inserts and label formats.
- Country-specific return addresses and return portals rather than one address for the whole region.
- Complete customs data on Norwegian shipments, including the VOEC number, HS codes and values.
- Batch and expiry handling on a FEFO basis where the product requires it.
- Carrier selection per destination country instead of one regional default.
What Each Category Demands
- Fashion: the highest return rates in the region. Budget for inspection, steaming or repackaging and fast putaway, and confirm how returns are billed.
- Electronics: serial number capture, warranty flows, secure storage, and national registration duties for packaging and electrical waste in each country.
- Home and garden: bulky and seasonal. Pallet-based storage, kerbside or two-person delivery, and a demand peak in spring and early summer.
- Sports and outdoor: friluftsliv drives sharp seasonality, skis and winter equipment in one half of the year and hiking and cycling in the other, with oversized items that carriers price separately.
- Food and supplements: FEFO, temperature control and the Norwegian VOEC exclusion described above.
Put together, the demand side leads to one warehousing conclusion. If Norway is a serious part of the plan, or if delivery speed is your competitive lever, a Nordic stock location earns its higher cost base. If the Nordics are one of several European markets and Norway is marginal, a continental European warehouse with strong linehaul into Denmark and Sweden usually wins on total cost. The Denmark example earlier in this article shows what the first option looks like in practice.
Where Your Nordic Stock Should Sit
Option A
Continental EU warehouse, Norway under VOEC
One stock location in the Netherlands or another continental hub. OSS for Sweden, Denmark and Finland, VOEC on Norwegian B2C parcels.
- The Nordics are one of several European markets
- Norway is a minor share of your orders
- Two to four day delivery outside the core is acceptable
Warehousing & fulfilment in the NetherlandsE-fulfilment in the NetherlandsFiscal representation & Article 23
Option B
Nordic stock in Denmark or Sweden
A warehouse inside the Nordic Trade Triangle. Day 1 domestically, day 1 to 2 into the Swedish and Norwegian core, with Norwegian parcels still crossing a customs border.
- Delivery speed is your competitive lever
- Nordic volume justifies a second stock point
- You sell through CDON, Boozt or Zalando and carry the delivery promise yourself
What Nordic fulfilment from Denmark costsE-commerce fulfilment in EuropeBest warehousing locations in Europe
Option C
Stock inside Norway
A Norwegian 3PL, Norwegian VAT registration and, for most non-EEA sellers, a VAT representative. The only route for goods VOEC excludes.
- Required for foodstuffs, beverages and supplements
- Sensible for B2B volume and items above NOK 3,000
- Norwegian returns are handled locally instead of re-imported
Food & nutrition logistics in the NordicsFMCG logisticsCold chain logistics
Choosing the Right Location in the Nordics
Several factors should influence your location choice within the Nordics:
- Target Market: Which countries are your primary focus? Consider proximity to your customer base and the efficiency of distribution networks.
- Industry Focus: Certain hubs specialize in particular industries (e.g., pharmaceuticals in Copenhagen, maritime logistics in Gothenburg/Bergen). Align your location with your industry's needs.
- Cost Sensitivity: Operating costs vary considerably across the region. Balance infrastructure advantages with cost considerations. Norway generally has the highest operating costs.
- Labor Market: Labor availability and costs are key factors. Research the labor market dynamics of each region and assess potential challenges.
- Brexit Impact: Consider potential impacts of Brexit on supply chains and access to European markets, especially for Denmark.
- E-commerce Strategy: If e-commerce is a significant part of your business, prioritize locations with strong e-commerce infrastructure and last-mile delivery capabilities (PostNord, 2024).
- Sustainability Goals: Align your location choice with your company's sustainability goals. The Nordic region offers numerous opportunities for green logistics operations, particularly in Norway and Finland.
- Data Center Needs: If your business requires significant data storage, consider Iceland or other Nordic countries with plentiful green energy resources and favorable climates for data centers (Infrastructure Investor, 2023).
Market Entry Checklist:
- Regional Selection: Based on the strategic considerations above, narrow down your potential locations.
- Infrastructure Assessment: Evaluate the transportation network, warehousing facilities, and other logistical resources available in your chosen region.
- Cost Analysis: Conduct a thorough cost analysis, including labor, rent, utilities, transportation, and taxes.
- Regulatory Compliance: Understand and comply with local regulations regarding building permits, environmental certificates, safety documentation, and labor laws.
- Local Expertise: Engage local experts for guidance on market entry, regulatory compliance, and operational best practices.
Market Trends Shaping the Future:
The Nordic logistics market is dynamic and evolving. Key trends to consider include:
- Sustainability: Stringent environmental regulations and consumer demand are driving sustainable logistics practices, including green building certifications and carbon reduction targets.
- Automation: Continued adoption of automation technologies will reshape warehouse operations and address labor market challenges.
- E-commerce Growth: E-commerce will remain a key driver of warehousing demand and influence location preferences (PostNord, 2024).
- Data Center Boom: The Nordic region, with its abundant renewable energy resources and suitable climate, is expected to see significant growth in the data center industry (Infrastructure Investor, 2023).
By understanding the diverse characteristics of the Nordic logistics market, businesses can make informed decisions about their expansion strategies, select the optimal locations for their warehousing and 3PL operations, and capitalize on the region's numerous opportunities. Careful planning and a deep understanding of local market dynamics are crucial for success in this sophisticated and evolving landscape.
Common Warehouse Types in Scandinavia
Modern Warehouse Facilities
- Automated Storage and Retrieval Systems (AS/RS)
- Temperature-controlled facilities
- E-commerce fulfillment centers
- Cross-dock facilities
- Bonded warehouses
Industry-Specific Solutions
- Pharmaceutical storage (GDP compliant)
- Food grade facilities
- Automotive logistics centers
- High-tech storage facilities
Compliance and Regulations
Regional Considerations
- EU regulations (Denmark, Sweden, Finland)
- EEA regulations (Norway)
- Environmental standards
- Work safety requirements
- Quality certifications
Documentation Requirements
- Import/export documentation
- Customs declarations
- Safety certificates
- Environmental compliance
- Labor regulations
Market Players
Major 3PL Providers
- DSV AS
- PostNord Logistics
- DB Schenker Nordic
- Bring
- DFDS Logistics
Real Estate Developers
- Logicor
- Prologis Nordic
- NLP (Nordic Logistics Properties)
- Sagax(opens in new tab)
- Castellum
- CBRE(opens in new tab)
Pricing and Costs
Warehouse Rental Rates (2023)
- Premium locations: €85-140/m²/year
- Secondary locations: €60-85/m²/year
- Developing areas: €40-60/m²/year
Operating Costs
- Labor: €35-45/hour (average)
- Utilities: €8-12/m²/month
- Maintenance: €4-6/m²/month


